Category: Non-Video

  • Blue Diamond Growers Awarded National FFA’s Distinguished Service Citation for Giving Tuesday Contributions

    Blue Diamond Growers Awarded National FFA’s Distinguished Service Citation for Giving Tuesday Contributions

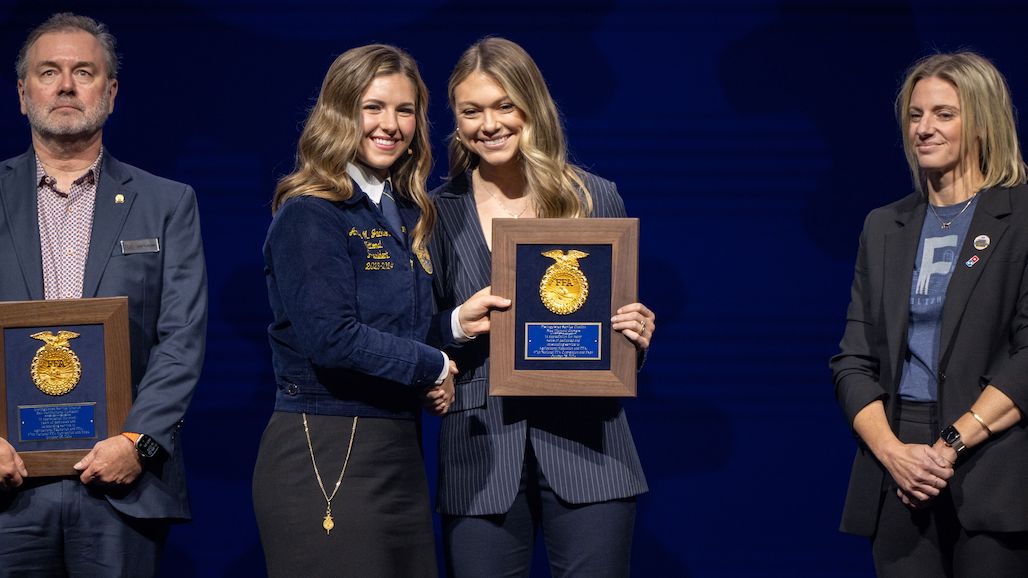
    Blue Diamond Growers was recently awarded the prestigious Distinguished Service Citation by the National FFA Organization at the 97th National FFA Convention and Expo in Indianapolis, Ind.

    The Distinguished Service Citation is an esteemed award honoring organizations, agencies, businesses, or other groups who have made outstanding contributions to FFA and agricultural education. Awardees must be nominated by a state association. Blue Diamond Growers was among the four awardees acknowledged at this year’s National FFA Convention.

    This year, the California Association FFA nominated Blue Diamond Growers, paying homage to their longstanding partnership on Giving Tuesday. This day is an annual tradition for FFA alumni, friends, and supporters to rally behind the California FFA Foundation’s “Give the Gift of Blue” initiative, which provides FFA jackets and uniform essentials to deserving FFA members.

    Set to be held on December 3 this year, the contributions made on Giving Tuesday are multiplied by the unwavering support of Blue Diamond Growers, who, since 2017, have pledged to match every donation up to $25,000.

    “This marks our eighth Giving Tuesday, a tradition of raising funds to ‘Give the Gift of Blue,’ in partnership with Blue Diamond Growers,” said Emily Rooney, chair of the California FFA Foundation and president of the Agricultural Council of California. “With the support of Blue Diamond Growers, we have raised over $463,785, providing 5,293 FFA jackets to members throughout California. We are delighted to see their efforts recognized by National FFA with the Distinguished Service Citation.”

    With California’s record-breaking membership of more than 104,000 middle and high school students, the demand for blue jackets has never been greater. The iconic blue jacket stands as more than just a part of the official FFA uniform; it also embodies the values of leadership and rich agricultural tradition instilled in FFA members for over 96 years.

    “We are extremely honored and grateful to have received the Distinguished Service Award from FFA,” said Steve Van Duyn, chairman of Blue Diamond Growers. “As a farmer-owned cooperative, we have a long history of supporting the next generation of agriculturists and food producers and are proud to continue this effort through our partnership with FFA.”

    Beyond Giving Tuesday, Blue Diamond Growers has been a steadfast ally to FFA and agricultural education, extending support through sponsorships of various proficiencies and awards. With 114 years of agricultural history in Northern California, and the participation of approximately 3,000 family growers responsible for producing almonds for the world, Blue Diamond Growers epitomizes a legacy of excellence.

    To discover more about the California FFA Foundation’s Giving Tuesday initiative or to contribute, please visit www.calaged.org/givingtuesday. Follow California FFA on Instagram, Facebook, or LinkedIn.

    About the California FFA Foundation

    California FFA Foundation serves more than 104,000 California students and strives to make a difference in their lives by developing their potential for premier leadership, personal growth, and career success through educational education. To learn more about the California FFA, visit calaged.org.

    About Blue Diamond Growers®

    Blue Diamond Growers, a grower-owned cooperative representing over 3,000 of California’s almond growers, is the world’s leading almond marketer and processor. Established in 1910, it created the California almond industry and opened world markets for almonds. Blue Diamond is dedicated to delivering the benefits of almonds around the world and does so by providing high-quality almonds, almond ingredients, and branded products. Headquartered in Sacramento, the company employs more than 1,600 people throughout its processing plants, receiving stations and gift shops. To learn more about Blue Diamond Growers, visit www.BlueDiamond.com and follow the company on Facebook, Instagram, LinkedIn and Twitter.

  • New Frosted Brownie Almonds for the Holidays

    New Frosted Brownie Almonds for the Holidays

    To kick off the holiday season, Blue Diamond, the world’s leading almond marketer and processor, today announced the launch of a new seasonal flavor: Blue Diamond Frosted Brownie Almonds. A]er exploring over 60 different holiday flavors and experimenting with 11 variations of frosted brownie, Blue Diamond has crafted a unique, festive treat that combines the flavors of rich chocolate and creamy frosting with the signature crunch of almonds creating an irresistible holiday snack.

    “We like to consistently test different flavor innovations, especially around the holidays, to expand our product portfolio based on what we know consumers are craving,” said Maya Erwin, Vice President of Marketing & Innovation at Blue Diamond. “Chocolate and the holidays go hand in hand, so we created Frosted Brownie to lean into this seasonal flavor, allowing snackers to enjoy the rich and creamy indulgence of a brownie, all with the crunch and goodness of an almond.”

    This is the third year Blue Diamond has released limited-edition holiday flavors, following last year’s soaring sales of Blue Diamond’s returning flavor, Snickerdoodle, highlighting the strong consumer demand for seasonal flavor offerings. Returning once again for 2024, consumers can enjoy the delicious cinnamon sugar cookie taste of Blue Diamond Snickerdoodle Almonds that they’ve come to love over the past two years.

    Blue Diamond is known for its unique lineup of craveable flavors such as Ranch, Thin Dipped and Chilé ‘N Lime and will increase its lineup of 20+ flavors with this latest holiday flavor expansion.

    From now through December 2024, holiday fanatics can find these holiday almond flavors in 6oz cans at major retailers nationwide and Amazon.com (MSRP: $4.29). For more information on existing and new products, visit BlueDiamond.com.

  • California Walnut Crop Mid-Harvest Update

    California Walnut Crop Mid-Harvest Update

    Fall is here, and the California Walnut Commission is pleased to provide a mid-harvest update on the 2024 walnut crop. With harvest progressing smoothly, we are excited to share some positive developments.

    While early varieties of California walnuts are nearing completion, the California-developed Chandler variety is at the peak of harvest and the industry is pleased with the quality of this year’s crop. Reports indicate that the walnut crop held up well to the summer temperatures, which were less severe than temperatures seen in 2022. The Chandler variety, which represents over 65% of the California industry acreage, shows excellent color and condition. With the continual advancement of optical sorters and enhanced inspections, processors can remove imperfect walnuts prior to the final pack and provide the high quality product customers expect.

    Gary Thiara, President and CEO of Empire Nut Company

    Gary Thiara, President and CEO of Empire Nut Company, stated, “The quality of walnuts this year is very good and meets the high expectations of our global buyers.”

    Additionally, demand for California walnuts is strong with early bookings for new crop already shipping to many global markets. The robust demand underscores the recognition of California walnuts as a premium product.

    In addition to providing a world class product, food safety is a top priority for the California walnut industry. Our walnuts are grown, harvested, and processed under stringent regulations, adhering to both federal and state food safety regulations. This commitment to food safety ensures that consumers receive a high-quality, safe product.

    The 2024 estimated crop size of 670,000 tons (607,814 MT), while moderate, is large enough to meet the current demands. The California Walnut Commission continues its efforts to expand and develop export markets, building more consumer excitement for premium, nutritious California walnuts around the world. We look forward to the successful completion of the harvest and continuing to meet the high demand for our walnuts.

    Note: The official 2024 California walnut crop production will be released in January 2025.

    About the California Walnut Commission

    The California Walnut Commission (CWC) represent more than 4,600 California walnut growers and nearly 70 handlers, grown in multi-generational farmers’ family orchards. California walnuts, known for their excellent nutritional value and quality, are shipped around the world all year long, with more than 99% of the walnuts grown in the United States being from California. The CWC, established in 1987, is involved in health research with consuming walnuts as well as domestic and export market development activities.

    To explore recipes and learn more about California walnut growers, industry information and health research, visit walnuts.org.

  • Smoke from Megafires Reduces Nut Crop Yields

    Smoke from Megafires Reduces Nut Crop Yields

    Long-term smoke exposure from massive wildfires lowers the energy reserves of orchard trees and can cut their nut production by half, researchers at the University of California, Davis, found. The smoke can affect trees for months after a megafire, depressing their bloom and the next season’s harvest. This finding reveals a new danger from wildfires that could affect plant health in both agricultural and natural environments.

    Nature Plants published the study on Oct. 2nd.

    “A lot of research focuses on the impact of smoke on humans but there is less study on the effects of smoke on plant health,” said lead author Jessica Orozco, a postdoctoral researcher with the UC Davis Department of Plant Sciences. “Our study suggests that trees are just as vulnerable as humans.”

    Wildfire smoke blocks sunlight

    Scientists studied almond, pistachio and walnut trees at 467 orchard sites in California’s Central Valley from 2018 to 2022. In 2020, megafires scorched more than 4.2 million acres in California, filling the skies with smoke and ash. At the time, researchers were studying how trees store energy, in the form of carbohydrates, to cope with heat and drought. But Orozco said the team saw an opportunity to study how smoke affects carbohydrate levels.

    “Photosynthesis produces carbohydrates, which are critical elements for tree survival,” said Orozco. “Trees need carbohydrates not just to grow but to store energy for when they’re under stress or when photosynthesis isn’t happening.”

    Photosynthesis changes under smoke-filled skies. Smoke particles block some sunlight but also reflect light, creating more diffused light. The diffused light can help trees make more carbohydrates. However, Orozco said the study found that while diffused light increased, the smoke was so thick that it likely didn’t compensate for the loss of direct light.

    Megafires have lingering effects on tree health

    The team found that megafire smoke not only reduced the amount of carbohydrates in trees but also caused losses that continued even after the fires were out. This led to nut yield decreases of 15% to as much as 50% in some orchards. The most active time for wildfires also coincides with the time trees start storing carbohydrates to sustain them through winter dormancy and spring growth.

    “We were expecting to see some impact especially in the months when the smoke was really dense, but we weren’t expecting the smoke to have such a lingering effect and result in a significant drop in yield,” Orozco said.

    Orozco said researchers still don’t know what components in megafire smoke caused the decrease in tree carbohydrates. During the 2020 megafires, the smoke reduced light and increased both ozone and particulate matter levels, all of which affect photosynthesis. One or a combination of these factors could have led to the drop in tree carbohydrates.

    Additional authors on the study are Professor Maciej A. Zwieniecki and postdoctoral researcher Paula Guzmán-Delgado of the UC Davis Department of Plant Sciences.

    The Almond Board of California, the California Pistachio Research Board, the California Walnut Board and the California Department of Food and Agriculture supported the research.

  • Setton Partners with FFA Tulare Chapter to Enhance Environmental Education

    Setton Partners with FFA Tulare Chapter to Enhance Environmental Education

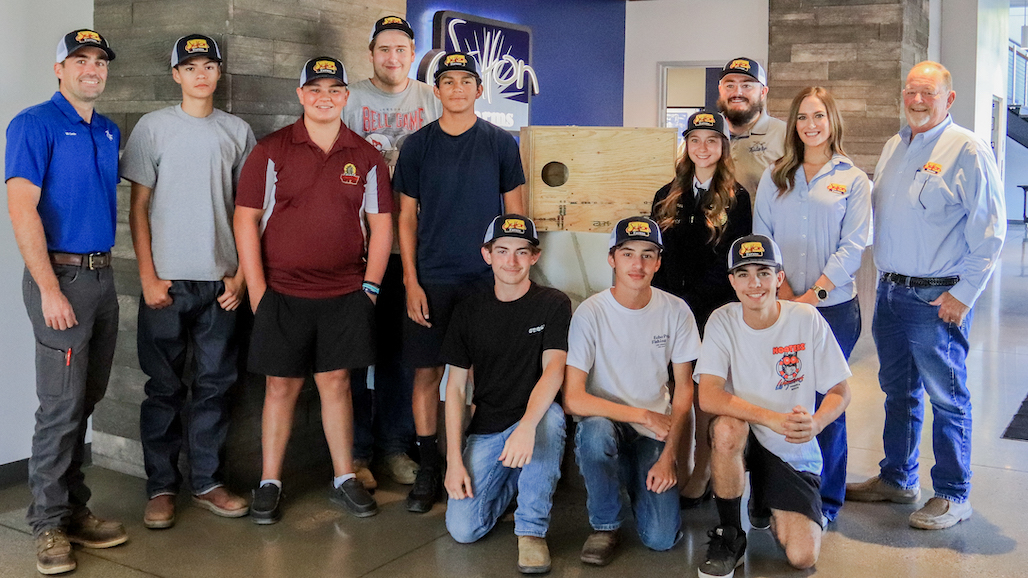
    Setton Pistachio of Terra Bella, Inc., the nation’s premier pistachio grower and processor, collaborated with the Future Farmers of America (FFA) Tulare chapter, including Mission Oak, Tulare Union, and Tulare Western high schools, to acquire 50 student-made owl boxes to help promote natural pest control in its orchards. For more information about Setton’s sustainable farming initiatives, visit SettonFarms.com.

    “We are thrilled to support the talented students of the Tulare FFA Agriculture Mechanics Program and their innovative approach to environmental stewardship,” said Jeff Gibbons, Senior Director of Grower Services & Farming. “Through this collaboration, we are reinforcing our commitment to our local community, sustainable farming practices, and supporting the next generation of farmers.”

    The owl boxes, crafted as part of the students’ 2024 curriculum, promote natural pest control by providing safe habitats for owls in agricultural areas, such as pistachio orchards. Owls are regarded for their role in sustainably managing pest populations, thus avoiding artificial pest control methods.

    The owl boxes will be strategically placed within several of Setton’s organic pistachio orchards and Deer Creek Citrus’s citrus orchards to promote natural pest control methods. This collaborative effort is part of Setton’s broader sustainability plan – which includes water conservation and recycling, soil health, regenerative farming techniques, and alternative clean energy sources – t0 further its commitment to support education, environmental stewardship, and community engagement.

    “We are grateful for Setton’s support, which enables our students to bring their projects to life and make a tangible difference in our community,” said Jared Castle, Chair of the Tulare Agriculture Department. “This partnership benefits our local environment and inspires our students to continue their education in the trade, allowing the 450 agriculture mechanics students enrolled in our program to continue to build projects.”

    About Setton Farms:

    Setton Pistachio of Terra Bella Inc., the second largest pistachio grower-processor in the United States, is a family-owned and operated company located in the heart of Central Valley, California since 1986. Highly regarded as “America’s Best Tasting Pistachios” and widely recognized for its superior quality and tradition of excellence, Setton Farms grows, harvests, processes and manufactures pistachios using renewable energy, and eco-friendly and sustainable practices. Setton Farms, its retail brand, offers an established line of premium in-shell and kernel pistachio products that are non-GMO project verified, certified gluten-free, organic and kosher, while a select variety features the AHA heart-check mark. Setton provides pistachios to more than 60 foreign markets worldwide and distributes to wholesalers and retailers throughout the United States. For more information, visit settonfarms.com.

  • California Continues as EU’s Top Supplier of Tree Nuts

    California Continues as EU’s Top Supplier of Tree Nuts

    In 2023, the European Union (EU)-27 imported $6.5 billion in tree nuts from the world. The EU remains a net importer of tree nuts for all products as demand highly exceeds domestic production. The United States is the largest EU-27 tree nuts supplier, providing $2.4 billion worth of nuts, or 37 percent of total imports. Nuts continue to benefit from their positive image as a healthy snack and a good source of all macronutrients, including carbohydrates, healthy fats and protein. Consumers are also paying more attention to the origin of what they eat, seeking out locally grown products, including nuts. More eco-friendly production, packaging, and distribution are becoming more popular among European consumers, particularly in the northern countries.

    Executive Summary
    The EU Continues to be a Key Trading Partner for U.S. Tree Nuts

    In 2023, the European Union (EU)-27 imported $6.5 billion in tree nuts from the world. The United States, with $2.4 billion, is the largest EU-27 tree nuts supplier, accounting for 37 percent of total imports. Türkiye is the second largest supplier with 22 percent of imports, mainly hazelnuts, followed by Vietnam (cashews), and Chile (hazelnuts and walnuts). U.S. almonds (both in-shell and shelled) totaled $1.28 billion, followed by pistachios with $758 million and walnuts with almost $276 million. Within the EU, the most significant importers of U.S. tree nuts are Germany, Spain, and Italy.

    The Food Processing and Snack Industry Remain the Most Significant Buyers

    The snacking industry continues to work to satisfy the evolving consumer demands and preferences, offering consumers new products and ways to consume nuts. The trend towards healthy snacking and healthy indulgence continues to gain importance and consumers are paying more attention to their diets. Processed nuts, especially almonds, pistachios, and peanuts, continue to dominate the retail landscape, while the preference for unprocessed nuts remains strong for walnuts and pecans. With consumers increasingly looking for natural products with clean labels, this is likely to encourage more consumers to make the switch to unprocessed nuts, especially for use in cooking, as well as for snacking. Nuts will continue to benefit from their positive image as a healthy snack and a good source of macronutrients, including carbohydrates, healthy fats and protein. The relatively high protein content in nuts will also continue to support their popularity among vegans, vegetarians and flexitarians. The localization trend has also gained significant traction with consumers increasingly seeking out locally grown products, including nuts. More eco-friendly production, packaging, and distribution are becoming popular amongst European consumers, particularly in the northern countries.

    Tree nuts consumption has been affected by the current economic situation, specifically inflation. As a result, consumer purchase decisions are likely to favor staple food products or cheaper options, particularly in more price-sensitive countries. However, consumption forecasts show some positive results, and this market sector has high potential due to the products’ high nutritional value, which increases its attractiveness to consumers. In addition, snack food companies are investing in the efficiency and improvement of production processes to improve their competitiveness. Despite economic uncertainties, the sector has the potential to grow, which should encourage companies to maintain their investment plans and continue investing in innovation.

    Expanding Business in the EU Market

    Trade shows are an excellent opportunity to get to know the market and to meet potential importers. Some of Europe’s leading trade shows are:

    USDA-Endorsed Trade Shows:

    SIAL October 19-23, 2024 Paris, France
    Biofach February 11-14, 2025 Nuremberg, Germany
    Fruit Logistica February 5-7, 2025 Berlin, Germany

    ANUGA October 4-8, 2025 Cologne, Germany

    Other Relevant (Non-Endorsed) Trade Shows:

    Food Ingredients November 19-21, 2024 Frankfurt, Germany

    ISM February 2-5, 2025 Cologne, Germany

    PLMA May 20-21, 2025 Amsterdam, Netherlands

    Alimentaria March 23-26, 2026 Barcelona, Spain

    Snackex TBD 2026 Lisbon, Portugal

    New-to-market exporters interested in a better understanding of EU food regulations and market opportunities are encouraged to reference the Food and Agricultural Import Regulations and Standards (FAIRS) reports and Exporter Guides produced by our EU FAS Offices.

    U.S. Cooperators Active in the EU Market

    Trade associations like the Almond Board of California, American Pistachio Growers, and the California Walnut Commission continue to develop strategies for the EU market. These trade associations, in cooperation with FAS offices, work actively to further develop the market for U.S. tree nuts.

    Almonds, Shelled Basis Production

    The EU-27 is the single largest export region for California almonds, with Spain as the leading European importer. In 2023, the EU-27 represented 29 percent of California’s total almond exports.

    Spain is the EU-27’s largest producer of almonds. For Marketing Year (MY) 2024/25, the latest official forecast published by the Spanish Ministry of Agriculture, Fisheries and Food (MAPA) estimates a production of 110,242 metric tons (MT) (shelled basis). The Nut Production Board estimates a higher result to reach 125,000 MT. In 2023, the total estimated area in Spain planted with almond trees was 765,540 hectares (HA), of which 635,000 are in production. Of the area in production, around 80 percent correspond to non-irrigated and 20 percent to irrigated production. The organic production area exceeds 137,000 hectares, which represents almost 25 percent of the total productive area.

    The estimated production for the current campaign is partly due to the entry in production of more than 14,000 new hectares. The new hectares are mainly irrigated in the regions of Extremadura, Castilla-La Mancha and Andalucia. The entry in production of the new irrigated hectares, along with the spring rains and absence of frost, have partially mitigated the negative impact of the drought, with a higher incidence in the southern producing region and the non-irrigated orchards. Although not all regions have equally benefited from the spring rains, the worst fears that the MY 2024/25 harvest would again be seriously affected not only in terms of volume, but also in size as in the previous campaign, have partly disappear.

    Italy is the second largest EU-27 almond producer after Spain. Sicily and Puglia are the main almond- producing areas, accounting together for approximately 97 percent of total supply. Tuono, Genco, and Lauranne are the leading varieties grown in the country. Italy’s MY 2024/25 almond production is forecast to drop by 31 from the previous season, mainly due to the severe drought that affected Sicily and Puglia. Quality is expected to be good. MY 2024/25 almond area is forecast to decrease as farmers in Sicily grubbed up almond trees crushed by a devastating drought.

    Currently, Italian farmers are facing some challenges, such as high production costs, which result in farmers sometimes preferring to leave the fruit on the plant rather than harvesting, as well as strong competition from California.

    Trade

    Imports

    Tree nut imports are crucial for EU consumers. Traditionally, consumers prefer locally grown products mainly due to consumer loyalty and habits. However, EU consumption of nuts is higher than production, generating an increase in both domestic production and in imports. In MY 2022/23, the United States was the main almond supplier for European importers. U.S. almonds face competition from Australia and locally grown almonds, mainly originating in Spain. By volume, the main EU destinations for U.S. almonds were Spain, Germany, and the Netherlands. Many countries import large quantities of almonds destined both for domestic consumption and re-export markets, as well as for the food and snack industry.

    Exports

    The top destinations for EU-27 almonds in MY 2022/23 were the United Kingdom, Switzerland, and Turkey. The largest EU almond exporter is Spain, whose main customers are mainly other EU Member States.

    Walnuts, In-shell Basis

    Production and Crop Area

    Romania remains the largest walnut producer in the European Union. Most Romanian walnut trees are owned by small farmers, but there is an increasing commercial interest in establishing walnut intensive orchards. The number of walnut trees has been growing steadily, reaching 2.6 million trees in 2023, a nearly 30 percent expansion from 2020. The number of productive trees is expected to expand further due to earlier plantings encouraged by EU subsidies for fruit trees. However, heat and dryness risks require additional investment in the orchards to ensure profitability. In 2024, the prolonged heat waves and dry conditions impacted production, which is anticipated to fall by 3.3 percent as compared to the previous year. The yield per tree is anticipated to drop by nine percent, but an estimated increase in the number of the trees alleviated the harvest decline.

    In France, production is concentrated in southern France, in the Rhône-Alpes, Aquitaine and Midi- Pyrénées regions. The French walnut grove has become the second largest orchard in France in terms of surface area. Along with kiwifruit, walnuts are the only fruit crop whose surface area has increased in ten years. The MY 2023/24 crop was low due to adverse weather, late frost and drought in the summer. MY 2024/25 also experienced late frost in southwestern France but an excess of rain throughout the summer. The crop in the southeastern part of France is reasonable (noix de Grenoble), but the crop is again very low in the southwest (Noix du Perigord) with a crop less than half the average. Overall, the MY 2024/25 French crop will be low, but slightly above 2023.

    In Spain, the main walnut growing regions are Andalucia, Extremadura, Castilla-La Mancha, and the Valencia region. As of the date of this report, MAPA has not yet published the official walnut production data for MY 2024/25. If weather conditions remain favorable, Post expects a production of 16,000 MT for the current MY.

    Italy lost its walnut market leadership a few decades ago and now is a leading importer, mainly from the United States. Since farmers generally grow walnut trees for both timber and nuts, nut yields and quality have suffered. Leading walnut producing regions in Northern Italy are Veneto, Emilia- Romagna, and Piemonte, where farmers have established efficient and profitable orchards planted with Lara and Chandler varieties. In the South, most walnuts are cultivated in the Campania region, where the main varieties are Sorrento, Malizia, and Chandler. Italy’s MY 2024/25 walnut production is forecast to increase from the previous season thanks to favorable weather and new orchards entering production in Northern Italy. Quality is expected to be good and calibers are expected to be medium/smaller.

    Trade

    Imports

    The wide gap between EU walnut production and imports provides excellent opportunities for walnut exporters. The EU imports various types of nuts for direct consumption as well as for further processing and re-export within the region in different forms, such as salted, baked, fried, or mixed with other nuts. The main competitor of U.S. walnuts, other than local production, is Chile (off season).

    Exports

    EU-27 walnut exports are very limited. The top destinations for EU-27 walnuts in MY 2022/23 were the United Kingdom, Switzerland, and Turkey.

    Pistachios, In-shell Basis

    Production

    Pistachio is a traditional crop in Italy, especially in the Sicily region (Bronte area), which accounts for approximately 90 percent of total supply. In recent years, pistachio production has slightly expanded to other areas in Sicily and Basilicata, where newer and input-intensive orchards have been planted. Bianca (also called Napoletana) is the main pistachio variety grown in the country and is normally harvested in September. Since 2004, pistachio from Bronte has been awarded by the European Commission as a PDO (Protected Designation of Origin), distinguishing it from other pistachio varieties worldwide. Pistachio tree production is cyclical, bearing heavily in alternate years. Therefore, after the higher MY 2023/24 crop, MY 2024/25 will be a lower bearing year. Quality is expected to be good.

    The pistachio area in Spain continues to expand rapidly. The production area for the MY 2023/24, according to the latest Ministry estimate, is 78,495 hectares, which is an increase of 145 percent from 2,600 hectares in 2012. The crop adapts well to extreme climates and grows well in inland regions such as Castile-La Mancha, which currently comprises 76 percent of Spain’s pistachio planted area. This year, there will be a lower production in this region, as this year will be “off-year” in the cyclical production. However, this will be partially compensated with the new hectares coming into production.

    At the production level, more and more farmers are choosing to switch from traditional crops to pistachios, attracted by their profitability and resistance to adverse weather conditions. In addition, the projections for the coming years remain optimistic, supported by constant demand and new investments in the sector. Pistachios have, in fact, proven to be an attractive investment for both farmers, companies and investment funds. Farmers have seen pistachios as an opportunity for diversification and to improve their profitability compared to other more traditional crops. However, in recent years, investment funds have also begun to invest heavily in this sector, which has allowed the creation of larger farms based on economies of scale.

    The next five years will be key for the Spanish pistachio sector with much of the planted area coming into production. Spain has 70 pistachio processing plants, 50 of which are in Castilla-La Mancha, with a total capacity of 5,500 dry tons. Thus, if the sector is to remain competitive, the industry is obliged to accompany the agricultural sector in its evolution.

    Trade

    Imports

    Due to very limited production and high demand, the EU pistachio trade balance remains negative, which results in significant imports from the United States and Iran, who together account for 94 percent of total imports. However, the quality and reliability of U.S. pistachios are appreciated assets, making it the chief source of EU imports. In recent years, Turkey has continuously increased their market share, but is still very far from the main two origins.

    Exports

    EU-27 exports of pistachios are limited. The main destination for EU-27 pistachios in MY 2022/23 was the United Kingdom.

    Policy

    Aflatoxin Certification for Tree Nuts

    Aflatoxin certification is an import instrument for U.S. exporters of almonds, pistachios and peanuts to the EU. Information on the product specific programs is available from the respective commodity groups as well as from the USDA Agricultural Marketing Service (AMS).

    Almonds

    At the request of the Almond Board of California (ABC), AMS administers a program for aflatoxin testing of almonds destined for export to the European Union (EU) through the Pre-Export Certification program of ABC. For information on aflatoxin certification on almonds, please go to the links below:

    •   Almond Board of California (ABC)
    •   USDA-AMS Laboratory Approval Service – Aflatoxin Program


      1. Pistachios

        At the request of the Administrative Committee for Pistachios (ACP), AMS administers a program for aflatoxins and ochratoxin A testing of pistachios destined for the EU through the Pistachio Export Aflatoxin Reporting (PEAR) Program.

        AMS administers mandatory domestic aflatoxin requirements for pistachio nuts under Pistachios Grown in California, Arizona, and New Mexico (7 CFR Part 983) and administers mandatory import requirements for pistachio nuts under Specialty Crops; Import Regulations (7 CFR Part 999, Section 999.600). The regulations require domestic and import shipments of pistachios intended for human consumption to be tested for aflatoxin contamination by a USDA or USDA-approved lab.

        For information on aflatoxin certification on pistachios, please go to the links below:

        •   Administrative Committee for Pistachios (ACP)
        •   USDA-AMS Technical Services – Pistachio Aflatoxin Program

          EU Import Controls on Food and Feed of Plant Origin

          Official controls are carried out by the competent authorities in the EU countries to verify business compliance with the requirements set out in agri-food chain legislation. Regulation (EU) 2017/625 of the European Parliament and of the Council of 15 March 2017 is the framework regulation setting common rules for carrying out these official controls. The scope of the regulation does not only cover food and feed safety throughout production, processing and distribution, but also covers plant health and plant protection, animal health and welfare, and organic production and labeling rules. Official controls can take place at all stages of marketing. The regulation also covers official controls on imports. A subsequent Commission notice on the implementation of Regulation (EU) 2017/625 of the European Parliament and of the Council (Official Controls Regulation) 2022/C 467/02 compiles further clarifications and best practices in order to contribute to a harmonized understanding and application of the provisions by Member States’ competent authorities and stakeholders.

          EU Controls on Almonds

          Almonds fall under a Pre-Export Checks regime. Regulation (EU) 2015/949 approves the pre-export checks carried out on certain food by certain third countries regarding the presence of certain mycotoxins.

          This regime is in place if a third country’s control system is accepted under Commission Implementing Regulation (EU) 2015/949. For the accepted product/origin combinations, the regulation requires that import authorities subject the consignments to less than a one percent physical control level at the border if they are accompanied by the appropriate pre-export check certificate. This document must be issued by the exporting country’s competent authority and include the sampling and laboratory analysis results. This documentation (government-issued certificate plus sampling/analysis data) is not a pre-condition for import. However, in the absence of this documentation, Member States are not required to apply the reduced testing levels upon import. Under this system, there is no charge to the operator for testing and the rejection rates are not specifically tracked or reported.

          For more information details, please check GAIN Report “EU Import Controls on Food and Feed of Plant Origin.”

          Maximum Residue Levels (MRLs) for Tree Nuts – Upcoming reviews

          Maximum Residue Levels (MRLs) for pesticides, including import tolerances, have been harmonized throughout the EU and can be found in the EU MRL database. Advance notice of active ingredients under review for renewal of approval in the EU, listed with a U.S. MRL, can be found in the global MRL database. For additional information, please consult the FAS/Brussels’ website on EU Early Alerts.

          Upcoming reviews for MRLs: Article 12 review: https://www.efsa.europa.eu/sites/default/files/pesticides-MRL-review-progress-report.pdf

          Maximum Levels for Contaminants in Food

          Maximum levels of aflatoxins (aflatoxins B1, B2, G1, G2 and M1) are laid down in Commission Regulation (EC) No 165/2010. The European Commission’s web page on contaminants provides further specific information on contaminants in general, and Plant toxins and mycotoxins and aflatoxins in particular.

          Commission Regulation (EU) 2021/1323, amending Regulation (EC) No 1881/2006 introduced maximum levels for Cadmium in certain foodstuffs.

          Commission Regulation (EU) 2022/1370, amending Regulation (EC) No. 1881/2006 as regards maximum levels of ochratoxin A in certain foodstuffs. — By Arantxa Medina, USDA Foreign Ag Service

          Disclaimer: This report presents the situation and outlook for tree nuts (almonds, walnuts, and pistachios) in the EU-27. This report presents the views of the authors and does not reflect the official views of the United States. Department of Agriculture (USDA). The data are not official USDA data.

          This report would not have been possible without the valuable expert contributions from the following Foreign Agricultural Service analysts:

          1. Xavier Audran, FAS/Paris covering France
            Mila Boshnakova, FAS/Sofia covering Bulgaria
            Ornella Bettini, FAS/Rome covering Italy
            Monica Dobrescu, FAS/Bucharest covering Romania
            Marcel Pinckaers, FAS/The Hague covering The Netherlands
            Gerda Vandercammen and Tania De Belder, FAS/Brussels covering EU policy

            Abbreviations and definitions used in this report:

            Conversion factors: conversion factor is used to convert shelled to in-shell tree nuts. Almonds: 0.6
            Walnuts: 2.34
            Pistachios: 2.0

            HA hectare; 1 hectare = 2.471 acres
            MT Metric ton = 1,000 kg
            EU MS European Union Member State(s)

            HS Codes: Harmonized System codes for commodity classification used to calculate trade data. Almonds: Shelled 080212; In-shell 080211
            Walnuts: Shelled 080232; In-shell 080231
            Pistachios: In-shell 080251, Shelled 080252 (since January 2012)

  • Indian Market Continues on Impressive Growth Trajectory for California Tree Nuts

    Indian Market Continues on Impressive Growth Trajectory for California Tree Nuts

    For marketing year (MY) 2024/2025 (August-July), the USDA Foreign Ag Service (Post) forecasts India’s almond production marginally lower at 4,150 metric tons (MT) (shelled basis), compared to last MY estimates. For the same MY, post projects almond imports at 190,000 MT, up by six percent from the previous MY 2023/2024 estimates of 180,000 MT. Post is revising its earlier MY 2023/2024 import estimates to 180,000 MT based on the latest updated trade data. For MY 2024/2025 (September-August), post forecasts India’s walnut production at 33,200 MT (in-shell basis). For MY 2023/2024, post is revising its estimates lower at 33,000 MT as there were no seasonal rains in the state of Jammu and Kashmir, and soil degradation in the walnut regions has affected its production yield. For MY 2024/2025, post expects India’s walnut imports to reach 70,000 MT, a 17 percent increase from the previous MY estimates. India’s MY 2024/2025 (September – August) pistachio (in-shell basis) imports are forecast at 40,000 MT.

    COMMODITY
    ALMONDS, SHELLED BASIS

    PRODUCTION

    For marketing year (MY) 2024/2025 (August-July), post forecasts India’s almond production lower at 4,150 metric tons (MT) (shelled basis), owing to climate and soil challenges within the top almond producing states of Jammu and Kashmir and Himachal Pradesh. There has been a continued trend of high temperatures, a lack of soil moisture, and prolonged dryness (Figure 1) in these top growing areas, which indicates an ongoing threat to India’s almond orchards that results in damaged crops at the blooming stage and reduced fruit setting. Additionally, aging orchards and low yields are enticing farmers to shift away from almonds to more profitable, and government supported, apple cultivation.

    India’s Almond Production Locations: According to the National Horticulture Board 2021-2022 (First Advance Estimates), India’s Union Territory of Jammu and Kashmir has the country’s top almond production share (91.26 percent), followed by Himachal Pradesh (8.73 percent) and Maharashtra (0.09 percent). Popular varietals grown in India include the Shalimar, Makdoon, Waris, and Kagazi (thin shell). The Kashmir Horticulture Department actively promotes the production of Kagazi almonds due to its higher yields and late blooming characteristics. Shelling rates range between 20 and 30 percent for hard-shell varieties, and 40 percent for thin-shelled varieties.

    To revive local almond cultivation and production, the Jammu and Kashmir government in recent years has launched several schemes and initiatives. These include the High-Density Plantation Scheme (HDPS), establishment of nurseries exclusively for almonds, and the development and enhancement of irrigation infrastructure.

    CONSUMPTION

    For MY 2024/2025, post estimates an increase in almond consumption at 195,660 MT, rising in tandem with Indian consumers’ growing incomes. Post is revising MY 2023/2024 estimate to 187,290 MT on account of an expanding consumer base. The increased purchasing power and the preference for healthy and nutritious snack foods is expected to continue to drive the demand for almonds. Globally, India ranks second in terms of consumption of almonds.

    With limited domestic almond production of its own, India turns to imports to satisfy its cravings for almonds. Indian media sources highlight that India’s in-shell almond imports over the last decade have grown with an astounding compound-annual-growth-rate (CAGR) of 17.5 percent. Market reports (from 2021) report that per capita consumption of almonds is about 0.11 kilograms (kg), which is a jump from the per capita figure of 0.08 kg being reported in 2019. Despite being a major importer of almonds, India’s per capita consumption of almonds, due to its large population size, is lower than that of other markets but still has major potential for expansion as consumers shift from other snacks to greater almond consumption.

    Half of India’s population is under 30 years of age, and there is a rising awareness of health and nutrition that is increasing demand for almonds. Indian consumers value the nutrient-rich crunchy nut that is packed with protein, fiber, vitamin E, and antioxidants. Traditionally, almonds have been seen to help improve memory performance and as being heart healthy.4 However, Indian almond consumption is no longer based just on traditional, cultural habits, for example, eating of almonds (soaked in water) each morning to improve memory and for the festive season. They are now commonly used in several Indian sweets as well as health drinks, breakfast cereals, snacking nuts (i.e., salted, and spicy almonds, trail mix, etc.), chocolates, cookies and ice-cream. India is also set to see a growth in the imports of some derivative products of almonds such as almond milk, flour and butter. These factors will contribute to spur the growth in India’s food processing and personal care industries. Bulk sales, associated with business and corporate gift giving, are also expanding in popularity driving overall consumption numbers upward. The packaged almond snack market in India is projected to reach Indian rupees (INR) 1 billion ($12 million) by end of calendar year 2024.

    STOCKS

    For MY 2024/2025, post estimates India’s almond ending stocks lower at 29,000 MT on expectations of continued strong domestic demand.

    TRADE

    Imports: For MY 2024/2025, post projects almond imports at 190,000 MT, up by six percent from the previous MY 2023/2024 estimates. Post is revising its earlier MY 2023/2024 estimate to 180,000 MT based on the latest updated trade data. The removal of India’s 2019 retaliatory tariffs last year has strongly boosted U.S. almond exports and in value terms there has been a 30 percent growth.

    India is the top destination for U.S. almonds (Figure 2). Specifically, California- origin almonds in MY 2024/2025 account for roughly 86 percent of India’s overall almond imports; Australian- origin almond imports come in a distant second with 10 percent market share (See, Table 2). Almond imports from the United States and Australia are typically the in-shell nonpareil or Carmel varieties, which are shelled locally (i.e., machine-cracked and hand sorted). By shelling the almonds locally, value addition occurs domestically; this contributes to expanded Indian employment opportunities and helps with the Indian government’s “Make in India” initiative. Most other origins, however, supply shelled almonds.

    Though the sea freight rates oscillated between January 2023 and March 2024, almond shipments to India continued its rising trend due to growing demand.

    Exports: India, with limited domestic production of its own, will continue to have negligible exports for the foreseeable future. India’s exports will consist mainly of small quantities of branded almond snack food products being exported to neighboring countries in South Asia.

    POLICY

    India’s removal of its retaliatory tariffs in September 2023, has restored and expanded market opportunities for U.S. agricultural producers and manufacturers. The reduction of duty for almonds is from INR 41/kg to INR 35/kg on the applied rate for in-shell almonds (see, GAIN- INDIA | IN2023-0066 | Success Story – India Cuts Retaliatory Tariffs on U.S. Almonds-Apples- Walnuts-Chickpeas-Lentils).

    India’s Non-Tariff Barriers: India’s non-tariff barriers include stringent almond kernel quality standards as prescribed by the Food Safety and Standards Authority of India (FSSAI).5 These standards, as informed by local trade sources, are too strict to be widely applied across multiple commercial grades. These only create challenges, causing needless custom clearance delays.

    Traders sustain that there is a need for greater grading flexibility. Grading needs to account for varying commercial situations, including varietal differences, crop quality variability, and pricing differentials. It should not be largely premised on just physical parameters such as damage and the presence of foreign material.

    Read the full USDA Foreign Ag Service report, including detailed insights on walnut and pistachio production and market trends HERE.
  • Increase of Chilean Almond & Walnut Production/Exports Forecasted

    Increase of Chilean Almond & Walnut Production/Exports Forecasted

    The USDA Foreign Ag Serive (Post) projects increased production in both Chilean walnuts and almonds in marketing year (MY) 2024/25 due to high yields caused by plentiful rainfall and favorable temperatures. Post estimates walnut production will reach 195,000 metric tons (MT) in MY 2024/25, a 11.4 percent increase year over year. Walnut exports will total 192,500 MT (in-shell basis), which represents a 12.1 percent increase over MY 2023/24. Meanwhile, walnut area planted is projected to increase only slightly, continuing a trend from recent years of stagnating growth. Producers have shifted to more profitable crops such as cherries, lemons, and mandarins, and because of changes in land use as urban areas continue to expand in the central area of the country. For almonds, Post projects that production will reach 11,500 MT for MY 2024/25, a 1.8 percent increase over MY 2023/24. Chilean almond exports will total 7,600 MT, a 4.1 percent increase over MY 2023/24.

    Commodities:

    Walnuts, Inshell Basis

    Production:

    In MY 2024/25, due to high yields, Post estimates walnut production at 195,000 MT, a 11.4 percent increase year over year. Post expects yields to increase in MY 2024/25, due to a winter with abundant rainfall and chill hour accumulation, and assuming no unexpected climatic events during the spring and summer which could lower production. In MY 2023/24, yields were low as production was hindered due to unfavorable climatic conditions.

    Post expects area planted in MY 2024/25 to increase slightly, by 0.8 percent, to 45,000 hectares because growth in the central-southern walnut production regions is offset by a decrease in the central- northern regions.

    In MY 2023/24, area planted decreased by 3.5 percent, totaling 44,626 hectares (Figure 1). Area planted is concentrated mainly in the central-south part of the country, specifically in the Metropolitana, O’Higgins and Maule regions, which together hold over 72 percent of the area planted (table 2). However, area planted in the Metropolitana region, the top walnut producing region in Chile, decreased by 5.5 percent. Walnut area planted was replaced by more profitable crops such as cherries, lemons, and mandarins, or was displaced by expansion of the urban area. Walnut area planted also decreased in the regions in the central-north part of the country, Valparaiso and Coquimbo. In these regions, area planted with walnuts was replaced mainly by citrus and cherries.

    Consumption:

    In MY 2024/25, Post estimates consumption at 2,850 MT, a 1.8 percent increase over MY 2023/24, following higher production and population growth which is situated at close to one percent annually. Producers export most of their walnut production, and domestic consumption of walnuts represents a little over one percent of total production. Local consumers use shelled walnuts for snacks. Walnuts for snacks are generally the highest quality in terms of color, size and shape. The confectionary industry uses fragmented walnuts as an ingredient in desserts, pastries, and chocolates.

    Trade:

    For MY 2024/25, due to higher production, Post projects 192,500 MT of walnut exports (in-shell basis), which represents a 12.1 percent increase over MY 2023/24. For MY 2023/24, Post estimates that walnut exports will finalize at 171,788 MT, which represents a 9.9 percent decrease from the previous marketing year.

    Figure 2 shows monthly export volume of walnuts. In MY 2023/24, monthly exports show low volumes compared to the previous marketing year, especially in May and June, which are regularly peak export months. The low exports volumes follow low production volumes and a reduction in walnut quality due to unfavorable climatic conditions.

    In MY 2023/24 (January to June data) exports decreased by 40.6 percent in volume and 32.2 percent in value (see Table 3 and Table 4). Post estimates that this high decrease in exports is due to the low export volumes observed in the first half of MY 2023/24. Post expects exports to increase in August and September, which are peak export months for Chilean walnuts.

    In MY 2022/23 Turkey, India and Italy were the top markets for Chilean walnuts. The Chilean walnut export industry has focused a lot of its marketing efforts in developing the Indian market. Exports to India increased by 108 percent and became Chile’s top market for in-shell walnuts, displacing Turkey, which had been the top market for in-shell walnuts in the past. On the other hand, the European market imports most of the Chilean shelled walnuts.

    Stocks:

    Post projects MY 2024/25 stocks at 4,000 MT, unchanged from the previous marketing year, assuming regular market conditions. Chilean walnut exporters do not store large quantities of walnuts unless there are specific market conditions that justify it, such as high freight costs or low prices. Post estimates MY 2023/24 stocks at 4,000 MT, which is a 29.5 percent increase over MY 2022/23. This increase is due to a lower quality crop, which decreased the share of almonds that complied with export quality requirements, which will result in an increase in stocks.

    Policy:

    No policy updates since the last GAIN report.

    Commodities:

    Almonds, Shelled Basis

    Production:

    For MY 2024/25, Post estimates almond area planted at 8,700 hectares, a 0.3 percent decrease over MY 2023/24 (see Table 5). Almond area planted spans from the Coquimbo region, in the northern part of the country, to the O’Higgins region in the central south. The top almond producing region in Chile is the O’Higgins region, which holds 37.7 percent of the area planted and which grew 11.1 percent in the past three years (table 6). On the contrary, the second top production region, the Metropolitana region, decreased by 13.3 percent in a three-year period. The Metropolitana region comprises 35.9 percent of the almond area planted.

    For MY 2024/25, Post projects that production will reach 11,500 MT, a 1.8 percent increase over MY 2023/24. This increase is driven by high yields and assumes no adverse climatic events that could hinder production. In MY 2023/24, almonds experienced adverse climatic conditions which lowered yields. As a result, Post estimates MY 2023/24 production volume will decrease by 9.6 percent and total 11,300 metric tons. However, almond production remains a good and relatively profitable alternative to other crops which have grown substantially in area planted, such as cherries, citrus, and walnuts.

    Consumption:

    In MY 2023/24, Post projects almond consumption at 7,700 MT, a 1.3 percent increase over MY 2022/23 due to population growth and a high demand for almonds. The domestic market for almonds is attractive for producers due to the competitive prices observed in Chile. Post estimates that 67 percent of commercial production is consumed domestically.

    Chile also imports almonds for use in the confectionary industry. The industry uses imported almonds to produce chocolates since they require smaller sized flat almonds that are not characteristic of the Chilean varieties.

    Trade:

    In MY 2024/25, Post estimates that total exports of Chilean almonds will reach 7,600 MT, a 4.1 percent increase over MY 2023/24 due to the higher yields and production volume. In MY 2023/24 (data until June), Chilean almond exports decreased by 20.5 percent in volume and 6.3 percent in value over MY 2022/23 (see Table 7 and 8). This decrease in exports follows the decrease in production.

    Figure 4 shows monthly almond exports. Almond monthly export volume in MY 2023/24 is lower compared to the previous marketing year. This reduction in exports is explained by lower almond production. Exports usually peak between June and October each marketing year since exporters can pack and store until they can allocate their exports and maximize their sale price.

    Top markets for Chilean almonds are Argentina, Russia, and Ecuador. Exports to Argentina grew by 10.2 percent in MY 2022/23. Exports to Russia grew by 59.6 percent as market conditions for Chilean exporters recovered in MY 2022/23. Ecuador remains the third top market for Chilean almonds, although almond export to Ecuador decreased by 10.5 percent in MY 2022/23.

    Post estimates that in MY 2024/25 almond imports will increase by 14.3 percent and total 4,000 MT to cover domestic consumption needs. Post expects an increase in imports as production remains virtually stagnant and consumption keeps growing at a moderate rate. The United States remains the top supplier of almonds to Chile. In MY 2023/24 (data until June), Chile imported 1,675 MT of almonds, representing a 3.3 percent increase over MY 2022/23. Ninety-nine percent of total almond imports were sourced from the United States.

    Stocks:

    Post estimates stocks in MY 2024/25 at 819 MT, a 32.3 percent increase, assuming higher production. Chilean almond exporters do not store large stocks of almonds, and stocks correspond to regular remaining monthly stocks.

    Policy:

    No policy updates since the last GAIN report. — By Sergio Gonzalez, USDA Foreign Ag Service

  • Record Turkish Pistachio Production Volumes Anticipated

    Record Turkish Pistachio Production Volumes Anticipated

    Turkey’s pistachio production in marketing year (MY) 2024/25 is forecast to reach a new record due to multiple factors. Higher production volumes and larger-than-normal carryover stocks are expected to prompt sizeable export volumes of Turkish pistachios for the first time. While Turkey’s production of tree nuts continues to grow, the country is expected to import substantial volumes of almonds and walnuts in MY 2024/25 to meet steady consumer demand. Imports of U.S. tree nuts continue to be disadvantaged by a 10 percent retaliatory tariff that was imposed because of U.S. Section 232 duties on Turkish steel and aluminum. However, despite this additional tax and growing competition, the United States is still the one of the top suppliers of walnuts, almonds and pistachios to Turkey.

    I. PISTACHIOS a. PRODUCTION

    Turkey’s pistachio production in marketing year (MY) 2024/25 is forecast to more than double year- over-year to a record of 385,000 metric tons (MT). There are multiple factors contributing to this projected increase, the most notable of which is this year is considered an “on-year” in the production cycle for pistachios. The growth in production is also linked to an increase in the number of bearing trees, higher yields as trees reach optimal bearing age, and favorable weather conditions during the growing season.

    According to the Turkish Statistical Institute (TurkStat), there were an estimated 60.5 million bearing pistachio trees at the beginning of the current marketing year, up nearly 4 percent from last year. Market sources confirmed that many of these trees are now approaching ten-years in age, which when yields start reaching their optimal range. This age-related yield factor will contribute to higher production volumes this year and in the years ahead.

    At the same time, there are about 26.6 million non-bearing trees, which is about 4.5 percent higher than a year ago. Turkey’s production of high-quality pistachios is predicted to increase in the future with the increasing number of young trees.

    Market sources indicate that TurkStat might be undercounting the actual number of bearing and non- bearing trees. However, even if the number of trees is being undercounted, TurkStat’s figures reconfirm the expansionary trend in the country’s production of pistachios.

    Over the last 10-15 years, pistachio growers have invested in developing and expanding their orchards, replacing old trees (some of which are 50-years old) and introducing modern growing techniques. These more sophisticated orchards with their newer trees, which are less affected by the periodicity in production, are expected to achieve higher yields and production volumes in the future. For the new trees being planted, market sources confirmed that growers are planting more of the Siirt variety compared to earlier years, known to be less periodical than the Antep variety. However, the Antep variety still accounts for most of the pistachio trees being grown.

    Good rainfall conditions in the spring of this year also contributed to the increase in pistachio production in MY 2024/25. Timely and adequate precipitation is critical since most pistachio production across Turkey is rain-fed.

    As seen in the Map 1, rainfall this spring in the southeastern part of the country, where most of the pistachios are grown, was near normal. A sunny summer, with no major weather events, and no unexpected pest attacks also promoted higher yields this year.

    Pistachio yields and production levels can vary dramatically from year-to-year with average yields during an on-year ranging from 4-6 kilograms (kg) per tree and 2-3 kg per tree during off-years. However, periodicity effects on yields have decreased in recent years with the planting of new trees, on- farm investments, and the introduction of good agricultural practices. At the same time, with the help of outside training provided by different institutions, farmers have learned how to reach higher yields by taking better care of the soil and trees. As a result of these improvements, average yields are expected to continue to slowly increase in the coming years.

    One of the more notable and ongoing training programs, called “May you have abundant pistachios,” was launched back in 2011 by the Turkish Foundation for Combating Soil Erosion, Forestation, and Protection of Natural Habitats (TEMA), with contributions from private companies. The initiative trains farmers in Gaziantep and Sanliurfa – the two biggest pistachio-producing provinces in the country – to properly care for their trees through improved pruning and trimming techniques, and better practices for applying fertilizer and pesticides. Farmers applying this training report seeing their yields double or even triple at times, while also reducing periodicity effects in off-years. In parallel to this training program, local universities in the major pistachio growing regions have developed better production methods and plant protection measures to help farmers improve yields.

    The two southeastern provinces of Gaziantep and Sanliurfa account for 80 percent of the country’s total production of pistachios. The southeastern provinces of Adiyaman, Siirt, Kilis, Kahramanmaras, Mardin, and Diyarbakir account for another 15 percent of total production. The remaining five percent is thinly spread across the Aegean, Mediterranean, and Marmara regions.

    There are two main types of pistachios grown in Turkiye, the Gaziantep (Antep) and Siirt varieties. Both are unique to Turkey and differ in size and shape compared to the pistachios grown in Iran and the United States. The Antep variety accounts for 85 percent of pistachios grown in Turkey. The Siirt variety makes up the remaining 15 percent of production; the Siirt variety is considered a higher-yielding variety than the Antep variety.

    The quality standards for Turkish pistachios are directly related to the size of the nut. 90 nuts or fewer per 100 grams is considered first quality; 90-100 nuts are second quality; 100-120 nuts are third quality; and more than 120 nuts are fourth quality.

    CONSUMPTION

    MY 2024/25 consumption is forecast higher year-on-year at 235,000 MT, based on a projected increase in domestic pistachio production and the expectation that traders will want to draw down their record- sized stock levels as much as possible.

    Turkiye continues to grapple with high inflation, including rising food prices. In August, the annual consumer price index (CPI) inflation was nearly 52 percent and annual food inflation reached almost 45 percent. See Post’s latest Exporter Guide for more information about the current economic conditions in Turkiye.

    In the case of pistachios, retail (and bulk) prices during the month of August were nearly 30 percent higher in terms of Turkish Lira (TL) than the same time last year. By comparison, though, the price in U.S. dollars (USD) was almost unchanged. See table 1.

    The reason retail (and bulk) pistachio prices (30 percent) did not increase as much as general food inflation (45 percent) was primarily due to the downward pressure on pistachio prices resulting from the anticipated record in production and large carryover stocks in MY 2023/24 and 2024/25. While still high, these relatively lower retail prices for pistachios will encourage increased consumption, especially among the upper-and higher-income households who are less impacted by the difficult economic realities in the country.

    Historically, most of the country’s pistachio crop is consumed domestically, though Turkiye is expected to export a share of its crop this year because of an anticipated oversupply. Consumption levels vary year-to-year depending on the availability of domestic supplies. About 35 percent of pistachios are consumed as snacks and the remaining 65 percent are used in making confectionary products, especially traditional desserts like baklava. In addition, during the last decade, more pistachios are being used in other desserts, such as chocolate and ice cream.

    In the last few years, consumers in larger cities increasingly prefer to buy packaged pistachios and other nuts from retail supermarkets instead of buying them from a traditional bulk nut store. This trend is expected to continue as consumers demand greater convenience and as more supermarkets spread across the country. For more information about the latest retail sector trends, please refer to Post’s latest Retail Food Report.

    Approximately half of the pistachios that are consumed for snacking are packaged. This percentage is expected to increase in the future as consumers demand greater convenience and shop at discount retail outlets where packaged food products are the norm. With this shift towards increased consumption of packaged pistachios, per capita consumption (2 kg/year) and overall consumption is expected to grow.

    b. TRADE

    Exports

    MY 2024/25 exports are forecast at a record 80,000 MT, assuming steady demand for re-exported pistachios and the potential for Turkiye to export domestic pistachios. Given the anticipated oversupply of domestic pistachios this year, Post expects Turkiye will export a sizeable amount of domestic pistachios to overseas markets this year. Up until this year, Turkiye only exported minor amounts of domestic pistachios, mostly in processed products. The bulk of Turkiye’s exports have historically consisted of U.S. and Iranian pistachios, which are sorted and packed in Turkish free trade zones and re- exported to third markets. Looking ahead, given the yearly fluctuations in domestic pistachio production, Post expects that the re-export business will continue to dominate overall exports for the foreseeable future.

    Turkiye predominantly exports shelled pistachios. The leading export destinations are Italy, Germany, Iraq, Syria, Malaysia and Saudi Arabia.

    Imports

    MY 2024/25 imports are forecast at 35,000 MT, which is down about 27 percent from the previous year’s newly revised figure as import demand is expected to slacken because of a record domestic harvest and large pistachio stocks.

    MY 2023/24 pistachio import volumes are revised higher to 48,000 MT in line with the latest trade data. The United States and Iran were the largest sources of imported pistachios, with U.S. pistachios accounting for 80 percent of total imports. According to market sources and Post observations, imported pistachios are typically not sold on the domestic market because of the high import taxes but are instead brought into free trade zones for processing and re-export. The absence of a bilateral phytosanitary protocol also discourages imported pistachios from entering the market for domestic consumption.

    The Most Favored Nation (MFN) duty on imported pistachios is 43.2 percent. However, since May 2019, imported pistachios from the United States have been subject to an additional 10 percent retaliatory tariff, bringing the total applied tariff rate to 53.2 percent. The retaliatory duty was imposed in response to U.S. Section 232 tariffs on Turkish steel and aluminum.

    c. STOCKS

    With the record harvest, year-end stocks for MY 2024/25 are forecast to more than double from last year’s newly revised estimate to 200,000 MT. This prediction assumes that traders will only sell off a portion of their inventories because stock levels are so large.

    MY 2023/24 ending stocks are revised higher to 95,000 MT based on an upward revision to the pistachio production number and in alignment with market expectations.

    Pistachio stocks vary considerably from year to year, in line with the cyclical nature of production. This cyclicality and the fact that neither the government of Turkiye (GoT) nor producer associations maintain ending-stock numbers leads to speculation, price fluctuations, and artificially inflated prices. According to industry insiders, pistachio traders intentionally hold onto inventories longer than normal to drive domestic prices higher. Accurate end-stocks data would help stabilize price fluctuations and consumption levels, especially in off-years.

    Municipal governments in Gaziantep and Sanliurfa have taken steps to increase transparency of pistachio stock levels in hopes of reducing speculation in the market. In June 2021, the Gaziantep Commodity Exchange (GCE) built Turkiye’s first licensed pistachio warehouse with a capacity of 10,000 MT. The warehouse has an electronic trading platform as well as a laboratory for quality testing. Sanliurfa Commodity Exchange has also invested in a licensed pistachio warehouse project with 10,000 MT of storage capacity.2 As these licensed warehouses represent just a small fraction of overall production, more of these facilities are needed to increase market transparency on the status of domestic stock levels. The government operates licensed warehouses for other crops, such as wheat, sunflowerseed, and cotton to create price stability.

    Scientists from various local universities continue supporting research applications to improve storage conditions, which is important in maintaining the quality of pistachios and in helping minimize food safety concerns, such as aflatoxin.

    d. POLICY

    Changes on the Horizon for Agricultural Support Payments

    While the central government does not provide specific, direct support payments to pistachio or other tree nut growers, the government does offer generic subsidies that are available to all registered farmers. The amount of generic subsidies in 2024 were up year-over-year in Turkish Lira but were nearly unchanged in USD. Pistachio growers and other farmers continue to complain that the subsidy this year, like the past several years, is inadequate to cover the rising cost of inputs, such as electricity, labor, and water.

    On August 29, 2024, the GoT announced in a Presidential Decision Decree (PDD) that it was instituting

    a new support system that would come into effect for 2025-2027. The payment under the new system is based on a calculation in which a standard coefficient amount per decare (da) for all crops that is multiplied by a multiplier factor depending on the crop. For 2025, the coefficient has been set at 244 TL/da and the multiplier for tree nuts is fixed at the lowest level of just one. (Note: Other crops, which are considered more strategic like wheat, have a higher multiplier factor.) Thus, tree nut farmers will receive 244 TL/da (=244 TL/da x 1). The coefficient may be updated each year, depending on the overall market conditions and economic situation in the country.

    Additionally, a subsidy payment will be paid for some products each year. The products and amount of the subsidy to be paid will be declared each year depending on needs of the country. Tree nuts are not expected to get a subsidy but only the basic support (as defined in this paragraph) starting 2025.

    Grower Groups Advocate for Gov’t to Set Purchase Prices for Pistachios

    Some agriculture-related non-governmental organizations (NGOs) in the Sanliurfa and Gaziantep provinces are demanding that the GoT, through the Turkish Grains Board (TMO), establish official purchase prices for pistachios like it does for hazelnuts. These groups argue that pistachios are just as strategic as hazelnuts to the wellbeing of the Turkish economy. These groups are also advocating for specific, direct government subsidy for pistachio producers.

    While the national government has not actualized these demands, the Metropolitan municipality of Gaziantep – one of the two largest pistachio- producing provinces – appears to have taken some small steps towards establishing a set price when purchasing pistachios from local growers. In late August 2024, the municipality started purchasing pistachios for making baklava and storing these nuts in the licensed pist

    achio warehouse that is operated by the Gaziantep Chamber of Commerce. At the same time, the Sahinbey district municipality in Gaziantep also started purchasing pistachios for making baklava.

    The Mayor of Sahinbey announced that the municipal government had started purchasing pistachios to keep traders from manipulating the market and stabilize prices. Supermarket chains and nut retailers have lodged similar complaints in the past. Post concurs with these claims, though prices in MY 2024/25 should soften due to increased supplies.

    Gaziantep metropolitan municipality’s purchase price is between 250 to 310 TL/kg (7.35 – 9.12 USD/kg), depending on product quality.  The price for same product in Gaziantep Commodity Exchange is between 265 to 320 TL/kg. (7.79 – 9.41 USD/kg), as of early September.

    Pistachio Imports for Consumption Considered One Potential Solution to Artificially High Prices

    According to industry analysts, there are some traders and retail chains that are advocating for the GoT to remove/lower the import tariffs and other trade barriers that would enable price-competitive, imported pistachios to enter the local market and, thereby, help stabilize the domestic price for pistachios. From Post’s perspective, imports for consumption would definitely have a stabilizing effect considering that exports of in-shell U.S. pistachios from January-July of this year cost about 6.80 USD/kg whereas the retail price in Turkiye for domestic pistachios is currently around 17 USD/kg.

    At the same time, market sources report that nut traders have petitioned the government to allow pistachios to be imported duty-free for processing and re-export under the Inward Processing Regime (IPR). The IPR allows companies to bring in certain goods tax free for processing inside the country and re-export. At present, pistachio imports can only enter duty free inside a tax-free zone. The IPR customs arrangement offers companies greater flexibility to process and re-export from anywhere in the country.

    Training Growers and Processors to Comply with EU Standards

    The Gaziantep Commodity Exchange (GCE), in cooperation with the German Institute of International Cooperation (GIZ), is conducting trainings for people who work or would like to work in the pistachio industry. These trainings include processing and roasting, marketing, foreign trade, and sustainability. Additionally, there are trainings, in cooperation with GIZ, for GCE member companies on topics covering the EU Green Transformation Agreement, EU Carbon Decreasing Mechanisms, EU Field to Fork Strategy, and EU Supply Chain Regulations. For farmers, there will be trainings about smart agriculture applications, reducing the use of pesticides and fertilizers, and pest management.

    For the full article from USDA Foreign Ag Service, including details on the Turkish almond, hazelnut, and walnut markets, click HERE.

  • Blue Diamond Growers Receives Cal/OSHA Recognition for Exceptional Safety

    Blue Diamond Growers Receives Cal/OSHA Recognition for Exceptional Safety

    Blue Diamond Growers, a farmer-owned Cooperative and the world’s leading almond marketer and processor, recently received the “Star Site” designation through Cal/OSHA’s Voluntary Protection Program (VPP) at their Salida Facility. The designation recognizes employers who have voluntarily managed outstanding safety and health programs. Only 63 sites within the state, including Blue Diamond, share the “Star Site” title.

    Beginning the formal process in 2023, Blue Diamond underwent the rigorous application to demonstrate exceptional safety at their Salida facility. This included numerous audits, formal interviews and a comprehensive review of their employee-driven program. As with all Star Site designees, the facility showed that their work-related injury and illness rates over the last three years (DART and TCIR) were 90 percent below industry average.

    “Through our partnership with Cal OSHA, we have elevated our safety program from best-in-class to world class,” said Victor Gomez Terres, Blue Diamond Site Director of Salida. “Safety at Blue Diamond is team member-led, and this designation is a culmination of their incredible effort and commitment to keeping themselves and each other safe.”

    Blue Diamond’s Salida facility has received and processed its farmers’ almonds since 1969. Today, it is the largest almond receiving center in the world. With eight warehouses and multiple processing lines, millions of pounds of almonds are either received or shipped out of the facility on any given day. The Cooperative’s ability to bring delicious, healthy products to the world would not be possible without its strong commitment to the health and safety of their 1,600 team members.

    “Blue Diamond’s success as the world’s largest almond company hinges on the safety of our operations and the wellbeing of our team members. I am proud that this milestone achievement validates our commitment to safety culture,” said Jeff Hatfield, SVP of Manufacturing for Blue Diamond.

    Coinciding with October as National Manufacturing Month, the Cooperative will hold a formal celebration and flag raising ceremony to honor team members and their partnership with Cal/OSHA.

    About Blue Diamond

    Blue Diamond Growers, a grower-owned cooperative representing over 3,000 of California’s almond growers, is the world’s leading almond marketer and processor. Established in 1910, it created the California almond industry and opened world markets for almonds. Blue Diamond is dedicated to delivering the benefits of almonds around the world and does so by providing high-quality almonds, almond ingredients, and branded products. Headquartered in Sacramento, the company employs more than 1,600 people throughout its processing plants, receiving stations and gift shops. To learn more about Blue Diamond Growers, visit www.BlueDiamond.com and follow the company on Facebook, Instagram, LinkedIn and Twitter.